

Disclosure: I own shares in HITI. I am not a professional. Please do your own due diligence.
High Tide is a retail-focused cannabis company with operations across Canadian cannabis retail, European medical cannabis distribution, and global e-commerce platforms. Its main retail banner is Canna Cabana, the largest cannabis retail chain in Canada, and its 51%-owned Remexian Pharma business imports and distributes medical cannabis in Germany.
Price: $3.54 CAD / $2.52 USD
MC: ~311 million CAD
EV: ~335 million CAD
1 year performance: +16%
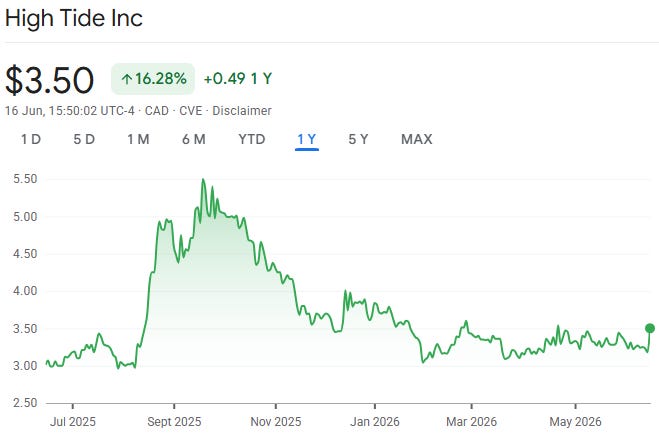
High Tide reported Q2 2026 results on June 15, 2026 after market close. Results were ahead my expectations and ahead of analyst estimates, with revenue 4.8% above estimate and adjusted EBITDA 35.6% above estimate. The stock was up 10-11% today.
all numbers in CAD unless stated otherwise
Quarter Recap
Q2 2026 Financials
Revenue: $179.3M vs $137.8M (+30.1% y/y)
Gross Profit: $48.4M vs $35.5M (+36.4% y/y)
Gross Margin: 27.0% vs 25.7% (+130 bps y/y)
Adjusted EBITDA: $13.9M vs $8.1M (+72.6% y/y)
Adjusted EBITDA Margin: 7.8% vs 5.9% (+190 bps y/y)
YTD
Revenue: $357.6M vs $280.3M (+27.6% y/y)
Gross Profit: $92.8M vs $70.9M (+30.9% y/y)
Gross Margin: 25.9% vs 25.3% (+60 bps y/y)
Adjusted EBITDA: $25.4M vs $15.2M (+67.5% y/y)
Adjusted EBITDA Margin: 7.1% vs 5.4% (+170 bps y/y)
Geographical Breakdown (Top Line & Profitability)
Canada revenue: $144.3M vs $133.1M (+8.4% y/y)
Canada gross profit: $39.7M vs $34.0M (+16.8% y/y)
Canada gross margin: 27.5% vs 25.5% (+200 bps y/y)
Canada income from operations: $5.9M vs $5.4M (+9.1% y/y)
USA revenue: $3.2M vs $4.5M (-30.3% y/y)
USA gross profit: $0.9M vs $1.4M (-37.4% y/y)
USA gross margin: 28.2% vs 31.4% (-320 bps y/y)
USA loss from operations: $(1.4)M vs $(4.2)M (loss improved 66.8% y/y)
International revenue: $31.8M vs $0.2M (n/m y/y due to Remexian)
International gross profit: $7.8M vs $0.0M (n/m y/y due to Remexian)
International gross margin: 24.4% vs 24.0% (+40 bps y/y)
International income from operations: $1.6M vs $(0.2)M
Segment and Other KPIs Breakdown
Bricks-and-mortar
revenue: $147.7M vs $137.8M (+7.2% y/y)
gross profit: $40.7M vs $35.5M (+14.7% y/y)
gross margin: 27.6% vs 25.7% (+190 bps y/y)
adjusted EBITDA: $10.7M vs $8.1M (+33.1% y/y)
adjusted EBITDA margin: 7.3% vs 5.9% (+140 bps y/y)
store count: 221 vs 195 (+13.3% y/y)
Same-store sales: -1.2%
Canadian Cabana Club members: 2.65M vs 1.91M (+39.0% y/y)
Canadian ELITE members: 178,000 vs 96,700 (+84.0% y/y)
Cabana Club members added over the last 12 months: 750,000
Canna Cabana market share: 12.0% vs 12.0% (flat y/y)
Average Canna Cabana store revenue versus peers: 1.9x
Shrink rate: 0.2% vs 0.3% (-10 bps y/y)
Stores opened during Q2: 3 new Ontario locations in Scarborough, Sarnia, and Caledonia
Quarter-end store count: 221 locations across Canada
Quarter-end store mix: Alberta 91, Ontario 97, Saskatchewan 13, British Columbia 8, Manitoba 12
White label SKUs: 41 vs not disclosed
White label sales mix: 1.7% of total bricks-and-mortar cannabis sales vs not disclosed
Medical cannabis
revenue: $31.6M vs $0.0M (new segment)
gross profit: $7.7M vs $0.0M (new segment)
reported gross margin: 24.4% vs n/a
adjusted gross margin: 27.0% vs n/a
adjusted EBITDA: $3.2M vs $0.0M (new segment)
adjusted EBITDA margin: 10.2% vs n/a
Remexian distributed volume: 7.6 tonnes
Remexian distributed volume sequential change: +21.0% q/q
Remexian revenue: $31.6M vs $25.0M sequentially (+26.6% q/q)
Remexian gross margin: 27.0% vs 12.0% sequentially (+1,500 bps q/q)
Remexian German market share: 14.0% vs 10.3% for the three months ended December 2025 and 6.5% for the three months ended September 2025
E-commerce
E-commerce reporting: e-commerce is no longer disclosed as a standalone operating segment and is now included in bricks-and-mortar. Numbers are pulled from US geographical disclosure
U.S. e-commerce proxy revenue: $3.2M vs $4.5M (-30.3% y/y)
U.S. e-commerce proxy gross profit: $0.9M vs $1.4M (-37.4% y/y)
U.S. e-commerce proxy loss from operations: $(1.4)M vs $(4.2)M (loss improved 66.8% y/y)
U.S. adjusted EBITDA improvement: $2.4M vs prior year
Conference Call Notes
Canada / bricks-and-mortar retail
Same-store sales were down slightly in Q2 and Q3 is tracking similarly, roughly down a point and change year over year.
Pressure is tied to format trade-down, lower visit frequency, and a more pressured blue-collar customer base, with customers trading down from eighths to ounce bags rather than leaving Canna Cabana.
Bricks-and-mortar gross margin reached 28.0%, with white label and ELITE remaining the main margin levers and the long-term gross margin target remaining 30.0%.
Canada store growth and M&A
Northern Helm generated $8.5M of annualized revenue and $1.7M of annualized adjusted EBITDA, with the acquisition priced at 4.5x annualized adjusted EBITDA.
Canada remains the top M&A priority, with High Tide looking for accretive acquisitions in markets where it does not already have a presence.
Ontario may consider increasing the retail store cap from 150 to 300; if that happens, High Tide would raise its long-term store target to more than 500 stores.
Canada market opportunity
Canada revenue potential was described as above $1.0B under the current opportunity set.
If Ontario increases the store cap, Canada revenue potential was described as $1.3B to $1.4B or more.
Ontario average Canna Cabana store revenue was cited at $2.7M vs peers at $1.1M.
Germany / Remexian
Remexian gross margin was 27.0% in Q2, and margins are expected to remain around 25.0%.
Q2 was described as more representative than Q1, though Remexian results are expected to be lumpier than Canadian retail because shipment timing can affect quarters.
Price compression is taking place in Germany, but Remexian is less affected because procurement costs have been reduced by 30% to 40% and supply has been diversified.
Germany supply chain
German import permits are taking approximately eight weeks, down from approximately thirteen weeks.
Portugal inventory declined from the original 15 to 17 tonnes to approximately 4 to 5 tonnes, with the most dated inventory released first.
Seven exclusive Canadian brands were launched or prepared for launch at Mary Jane.
Future international opportunities
The UK remains the European market of highest interest.
High Tide is speaking with larger operators and smaller specialized businesses.
Two additional European markets have generated inbound partner interest.
U.S. / e-commerce and optionality
U.S. e-commerce is now a minor component of the bricks-and-mortar segment.
The business has stabilized, U.S. EBITDA improved by $2.4M versus the prior year, and interested parties are at the table for the accessory side.
U.S. opportunities continue to be evaluated, but U.S. entry is not a near-term priority, and High Tide is considering scenarios that preserve its Nasdaq listing.
U.S. CBD optionality
NuLeaf Naturals is positioned around potential Medicare CBD pilot projects.
High Tide continues to monitor the U.S. CBD market.
Broader U.S. opportunities remain under evaluation.
Cash flow and working capital
Free cash flow was $1.5M in Q2.
Working capital investment was $4.3M, mainly for Remexian inventory and newly opened stores.
Without the working capital investment, free cash flow would have been approximately $6.0M.
Guidance & Outlook
They don’t give any formal guidance, but they do talk about long term targets and goals.
Store Count in Canada
Store growth: High Tide reiterated a target of 20 to 30 store openings in calendar 2026.
Current store count: Canna Cabana had 221 stores at quarter-end and 228 locations pro forma after subsequent openings and the announced Northern Helm acquisition.
Long-term store count: High Tide reiterated a long-term goal of more than 350 locations across Canada.
British Columbia store cap: British Columbia may eventually increase its store cap from 8 to 16.
Ontario store cap: Ontario may consider increasing the retail store cap from 150 to 300.
Ontario upside: if Ontario increases the store cap, High Tide will raise its long-term Canadian store target to more than 500 stores.
Canada Revenue & Memberships
Canada upside with Ontario cap increase: if Ontario increases the store cap, Canada revenue potential was described as $1.3B to $1.4B or more.
Canada revenue potential: Canada revenue potential was described as above $1.0B under the current opportunity set.
Cabana Club: High Tide expects more than 3.0M Cabana Club members in Canada over the long term.
ELITE: the long-term goal is to convert at least 50.0% of base tier members into ELITE.
White Label
White label: white label SKUs reached 41 and represented 1.7% of bricks-and-mortar cannabis sales.
White label target: white label sales are expected to reach approximately 20.0% of total bricks-and-mortar cannabis sales over the long term.
International
Germany market share: Remexian reached approximately 14.0% German medical cannabis market share for the three months ended March 2026.
Germany long-term share: High Tide is targeting approximately 20.0% German market share over the long term.
Remexian margin: Remexian gross margin is expected to remain around 25.0%.
Remexian volatility: German medical cannabis results may be more volatile than Canadian retail due to shipment timing.
UK expansion: the objective remains to complete a UK transaction within the next few quarters.
Europe expansion: High Tide is evaluating additional European markets, including inbound partner interest outside the UK.
Valuation
I have HITI at just under 7x EV/ttm EBITDA. I do not think that looking at ttm FCF will tell the story for HITI as the next 12-24 months will look quite different from the last 12. I have them around 9x CFFO for the full year 2026, which doesn’t include capex. They are at 6.2x EV/my estimate 2026 EBITDA.
The BMO credit facility is an important update because it gives High Tide a $40.0M senior secured facility, replaces connectFirst, provides expected revolver capacity, and should release approximately $7.5M of restricted cash after closing. I haven’t factored this into my valuation.
Closing Thoughts
The quarter included several moving pieces: stronger Remexian margins, continued Canadian retail expansion, weak but stabilized U.S. e-commerce, positive free cash flow despite working capital investment, and a new senior lender relationship with BMO.
Canadian retail same-store sales were down 1.2%, but total bricks-and-mortar revenue increased 7.2% and bricks-and-mortar adjusted EBITDA increased 33.1%. Store count reached 221 at quarter-end and 228 pro forma after subsequent openings and the Northern Helm acquisition.
The key items to monitor next quarter are Remexian margin durability, same-store sales weakness in Canada, working capital needs tied to Germany, and whether the BMO facility and Northern Helm acquisition close as expected.
HITI is not the cheapest name in my cannabis basket, but they have some pretty unique characteristics.
The sector is pretty out of favor so I wouldn’t be surprised if HITI gives back some of today’s gains. I am looking to continue to add to my position at these prices.
Thanks for reading my work.
Dean
long HITI
Was going to skim through it Dean, always interested in your thoughts, but couldn't.........is a flipping Marijuana company worth the time I thought. No, was the answer.
Maybe should have read, might change my mind on MJ investing.