

Disclosure: I own shares in ROMJ. I am not a professional. Please do your own due diligence.
Price: $0.46 CAD
Shares: 70.8 million
Market Cap: 31.9 million CAD
Enterprise Value: 34.6 million CAD
1 year performance: +38%
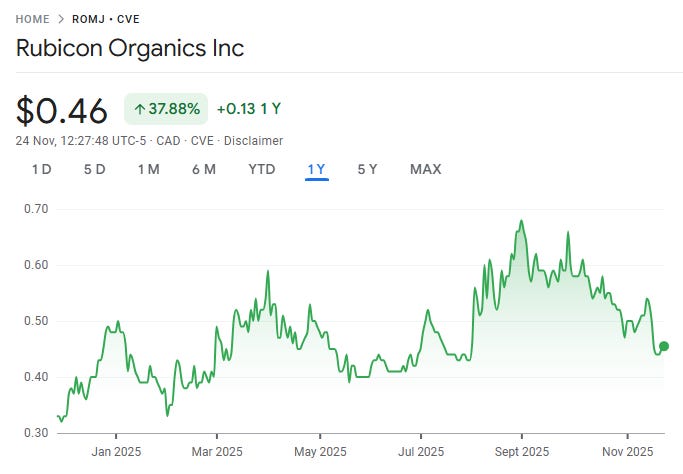
I have been building a basket of cannabis companies over the last couple of quarters. ROMJ has come on my radar as it’s been mentioned by Maxwell House, Stocks & Stones, Common Sense Investing, Mark E. Meritt and others. If it isn’t obvious, this isn’t an original idea.
Below you can see their presentation at the recent SCD conference in Vancouver as well as some other videos on YouTube.
Background
Rubicon Organics is a Canadian premium cannabis producer focused on certified organic cultivation. The company operates out of Delta, BC, where it produces flower and derivative products sold under brands such as Simply Bare Organic, 1964 Supply Co., and Homestead Harvest.
Its goal is to occupy the top end of the Canadian flower market—where pricing is firmer, brand loyalty actually matters, and consumers aren’t just chasing the product.
Recurring top-tier brand placement in major provinces
Margins trending upward as post-harvest processes improved
Inventory management now leaner vs past bloating
International shipments (Israel, Australia, Germany) beginning to matter
No major capex required, facility can support higher output
Improved cash generation vs early years where capital was constantly leaking
Facilities (more detail in a bit)
Pacifica (Delta, BC)
~125k sq ft
~10–11 tonnes/year today
No major expansion planned (focus on efficiency)
Cascadia (Hope, BC)
47.5k sq ft
Licensed Oct 2025
0 kg today → 4,500 kg/year by end of 2026
Adds +40% total capacity
Supports international strategy
Total Capacity Today: ~10–11k kg
Total Capacity 2026+: ~15.5k kg
Total Capacity 2027 Max: ~16k kg
Product Focus
Rubicon Organics sells a full premium product suite, anchored by organic indoor flower and supported by high-margin categories like vapes, pre-rolls, topicals and edibles. They operate as a branded cannabis CPG company.
Core Product Lines
1. Certified Organic Indoor Flower (Flagship)
Grown at the Pacifica facility (formerly Delta), ~10–11 tonnes annual capacity.
Known for stability in potency, terpene profile, and curing consistency.
2. Premium Pre-Rolls
Simply Bare & 1964 SKUs.
Pre-roll automation (installed 2025) reduced labour from 10 → 2 per shift and saves ~$1M annually.
Pre-rolls now ~35% of the Canadian rec market—this category is core to Rubicon’s growth.
3. Resin Vapes (1964)
Fastest-growing category in Canada.
1964 has jumped to ~13–15% national share in resin vapes.
7 SKUs in 2024 → ~11 SKUs expected through 2025–26.
All-in-one disposables launched mid-2025; management expects 4 SKUs by year-end.
4. Edibles
#1 in premium edibles with ~26% market share.
Award-winning SKUs—consistent rotation and limited-edition drops keep the flywheel spinning.
5. Topicals (Wildflower)
Wildflower is the #2 national topical brand with 28% category share.
Includes relief sticks, cool sticks, oils—category leader with strong retailer relationships.
6. Hash, Concentrates, Blunts
1964-branded resin, hash, milled flower, variety packs.
Reinforces terpene-driven branding across formats.
7. Homestead – Value-Tier Bypass Channel
Used for product not meeting premium specs (reported to be <5% of volume in 2025). The lower this is the better the product is at the facility.
Acts as a pressure-release valve so high-end brand equity stays uncompromised.
8. International SKUs (Emerging)
Medical-grade premium flower.
Initial shipments in 2025 to UK, Poland, Australia.
Full launch requires Cascadia capacity.
This provides additional upside to the investment thesis.
Facility Capacity Overview
1. Pacifica Facility (Delta, BC – existing/legacy)
Current Name: Pacifica
Size: ~125,000 sq ft
Current Capacity (2025) ~10,000–11,000 kg per year
Future Capacity
Pacifica is already running near full capacity and not expected to materially expand beyond the ~10–11 tonnes range because:
The facility is fully optimized.
Process improvements (automation, lighting trials) focus on yield & cost, not added footprint.
Incremental gains from R&D may improve cost per gram, not major kilograms produced.
2. Cascadia Facility (Hope, BC – acquired 2025, licensed Oct 2025)
Current Name: Cascadia
Size: 47,500 sq ft
Licensed: October 20, 2025
Purpose: Premium indoor production + international medical supply
Current Capacity (Late 2025 / pre-ramp)
Commissioning began Q4 2025
First harvests expected Q1–Q2 2026
First revenue expected H1 2026
Cascadia adds 4,500 kg of cultivation capacity
Represents +40% to Rubicon’s existing production
Additional upside expected with optimization
Combined Rubicon Capacity – Today and Future
Today (late 2025) – Pre-Cascadia Production
Pacifica: ~10,000–11,000 kg
Cascadia: 0 kg
Total: ~10,000–11,000 kg
Mid-2026 – Early Cascadia Ramp
Pacifica: ~10,000–11,000 kg
Cascadia: ~1,500–2,000 kg (early cycles)
Total: ~11,500–13,000 kg
End of 2026 – Cascadia Reaching Steady Production
Pacifica: ~10,000–11,000 kg
Cascadia: ~4,500 kg
Total: ~14,500–15,500 kg
2027 (full optimization)
Pacifica: ~10,000–11,000 kg
Cascadia: 4,500–5,000 kg
Total: ~15,000–16,000 kg
What Sets Them Apart
1 - Structural Differentiation
Both the Pacifica and Cascadia facilities are approved to sell cannabis. Getting certification from Health Canada to cultivate, process, and store cannabis is something that domestic LPs need.
Certification restricts pesticides, substrates, and environmental controls.
Retailers rely heavily on certifications when upselling premium consumers.
2 - Strategic Facility Acquisition Provides Cost Advantage
ROMJ has survived through the go-go days of legalization of cannabis here in Canada and has demonstrated cost discipline. Their ability to access capital when many other’s could not allowed them to scoop up the facility in Hope (Cascadia).
I estimate the all-in costs to be 8-9 million CAD. 4.5 million for the facility, 1-2 million in retrofit and capital and then some initial start-up operating costs of 2-3 million. They will see production in H1 2026 and I am estimating them to take a few harvests to fine tune things. The run rate EBITDA (my estimate) is 8-10 million.
3 - Strong Brand Equity in Canada
Rubicon isn’t just a grower—they have category-leading brands and are able to command a premium price.
Won “Flower of the Year” twice.
Won 7 of 11 Kind Awards in 2025, including Brand of the Year.
Retailers describe 1964 and Simply Bare as “trusted premium brands with consistent SKUs.”
Their focus on the high end of the market allows them to charge an above average price and keep mind-share with customers.
4 - International Potential Once Cascadia is Complete
ROMJ has been very deliberate in their expansion internationally. Several “test” batches have been sent out to ensure streamlined processes when they are ready to push the throttle harder on the international market. Once the Cascadia is stabilized, we could see a material contribution from international revenue.
5. Talent Density & Operational Discipline
The management team at ROMJ is strong.
CEO Margaret Brodie → disciplined, capital-efficient, excellent communicator.
CFO Glen Ibbott → former ACB CFO, deep industry knowledge, highly respected.
COO Melanie Ramsey → described as “could be a CEO anywhere.”
7 independent directors including policy experts (e.g., Karen Proud).
Investors consistently describe management as “punching above their weight.”
6. Retailer-Centric Sell-Through Strategy
Rubicon’s sales philosophy is:
Win the budtender (retail advocate).
Win the repurchase.
Win the recommendation cycle.
They use social feedback loops (Reddit, Instagram) and retailer interviews to iterate product. I was impressed at how on-the-ground they are with getting feedback on what customers are saying about their products. Other than aggregated sales data, it’s hard to get feedback on customer experiences and preferences due to regulation. ROMJ does a good job working around this.
7 - People Focus Creates Strong Culture
ROMJ utilizes many foreign workers at their facilities. They also have on-site housing to support these workers. Once on the payroll, employees become family. When I met with the CEO and CFO they were energized by the solid base of employees at each facility. The CEO even mentioned how she was proud of how the team performed at a local soccer league. It’s pretty rare to see such people-focused details from a CEO.
Balance Sheet
The balance sheet is strong here. They had a small amount of debt at end of Q3 at less than 3 million net of cash. Since then, ROMJ has secured an additional 3 million 5 year capital loan at 6.79% and a 1 million floating credit line.
The recent slug of capital gives them some breathing room to ramp Cascadia. Though I always like cheaper terms, as a microcap investor I’m glad they aren’t tapping the equity markets here.
Share Structure & Ownership
70 million shares outstanding.
70.9 million fully diluted.
The two co-founders (Eric Savics and Jesse McConnell) are the largest holders with about 35% between them.
Another board member owns 5%.
The CEO owns nearly 3%.
Management & Compensation
The CEO (Margaret Brodie) has been with the company since 2024. She has been with the business for several years beyond that. I consider her a strong and passionate communicator. She has been deliberate in focusing ROMJ on sticking to what they do best in the premium market. The test shipments internationally open up doors, but she has made it clear they aren’t betting the farm on it. She owns over 2x her salary in stock.
Glen Ibbot was recently promoted to CFO after being with the business for about 6 months. He was with Aurora Cannabis from 2017-2024, so he has been in the trenches for the good times and the bad. I often worry about executives who are part of an industry during a boom and the habits they learn when capital is cheap. I do not have that concern with Glen. He seemed reasonable and well versed on ROMJ in the couple of times I met with him.
Melanie Ramsey is the COO and has been with the company for several years and has navigated the ROMJ as they optimized yields at Pacifica. She will play a large role in Cascadia. Given her large role in this pivotal point in ROMJ’s journey, I would prefer to have more exposure to the share price.
The incentive plans focus on profitability, capital discipline and execution. The variable compensation is modest.
All together I have the executive team owning just over 3% of the common.
Board
The board has 8 members. 6 are independent with the CEO and one of the co-founders being the non-independent. The co-founder (McConnell) was nominated via a nomination agreement.
They are compensated via cash and DSUs. None of which seems to be egregious.
The board owns 26% of the common.
Investment Thesis
Overall this investment revolves around some key assumptions:
1 - Stable Domestic Market
The domestic market in Canada needs to remain stable or “stable enough”. No big sweeping (negative) changes with Rubicon maintaining their brand presence. I would characterize this as stable pricing, policy and gradual degradation in the illicit market.
2 - Increase in Capacity vis Cascadia
The investment and ramp up in Cascadia will give them visibility to a growing top line. This is something all investors appreciate as it’s so much easier to own things that are growing.
3 - International Expansion
Though I think ROMJ works without international revenue, it is a nice kicker. Once Cascadia is online, they will have some capacity for international revenue. By then we will have further visibility on how the rest of the developed world deals with cannabis.
4 - Team has been through the ringer
The industry has not been an easy place to build a career. I believe this provides some security in my investment as they have had to run a tight ship as the sector right-sized supply and demand.
5 - Other
There is the possibility of additional upside via a facility purchase or M&A. But that is not where my focus is for ROMJ.
Risks
Here are the major risks that I see for ROMJ.
Domestic market stability
Though the market in Canada has been improving. It is still an industry that is in it’s infancy. There is no guarentee that the market participants will continue to operate logically.
Brand value
ROMJ products are in the premium side of the market. Though consumers have been willing to pay for extra quality, this could change. It’s important for ROMJ to maintain presence here. Competitors could also come in and challenge the premium market.
International market opportunity
If other countries reverse their decision to have a legal cannabis market or if they are slower at opening up to Canadian LPs than expected, this could impact the international revenue component for ROMJ. They are not the only LP looking to get some international exposure.
US market
Though ROMJ does not have any US exposure, any headline risk for cannabis in the US likely bleeds into the Canadian stocks at least in the short term.
Quarterly lumpiness and Cascadia
I’m puting these two risks together as they are one and the same in the immediate term for ROMJ. They are still a small business that can have quarterly swings simply due to the nature of their business.
There could also be some delays or cost overruns at Cascadia that could set back the ramp up.
Something unforeseen that I don’t see coming
A strike of some sort. Something with a harvest. An issue with Pacifica. This is just a catch all of other potential issues that come with owning a small business.
Valuation
I have ROMJ at 5.2x EV/ttm EBITDA. I don’t think looking at ttm FCF is indicative of what the business will do as there are some costs associated with Cascadia. It really won’t be until well into 2026 that we get to see what the business can do at full capacity.
I estimate they are well under 10x FCF once Cascadia is producing consistently.
Closing Thoughts
ROMJ fits nicely in a cannabis basket for me. I like that there is visibility to how they can get a significantly higher top line from here. I have met the management team and view them as solid operators. The valuation is quite compelling and the industry still has little institutional interest.
Execution is positive. International optionality is real. Dilution risk is low. Premium cannabis continues to have pricing power.
Thanks for reading my work.
Dean
Disclosure – long ROMJ